If you share your home with a Dachshund, you have probably heard the warnings about their backs. Intervertebral disc disease, or IVDD, affects roughly one in four Dachshunds during their lifetime according to veterinary literature. That makes back coverage the single most important thing to understand before you buy a policy.
This guide explains how IVDD works, how insurers treat back issues, and which plan features actually matter for this breed. Get these details right and a Dachshund policy can be one of the smartest purchases you make. Get them wrong and you may find the exact condition you feared is excluded.
Why Dachshunds Are Prone to IVDD
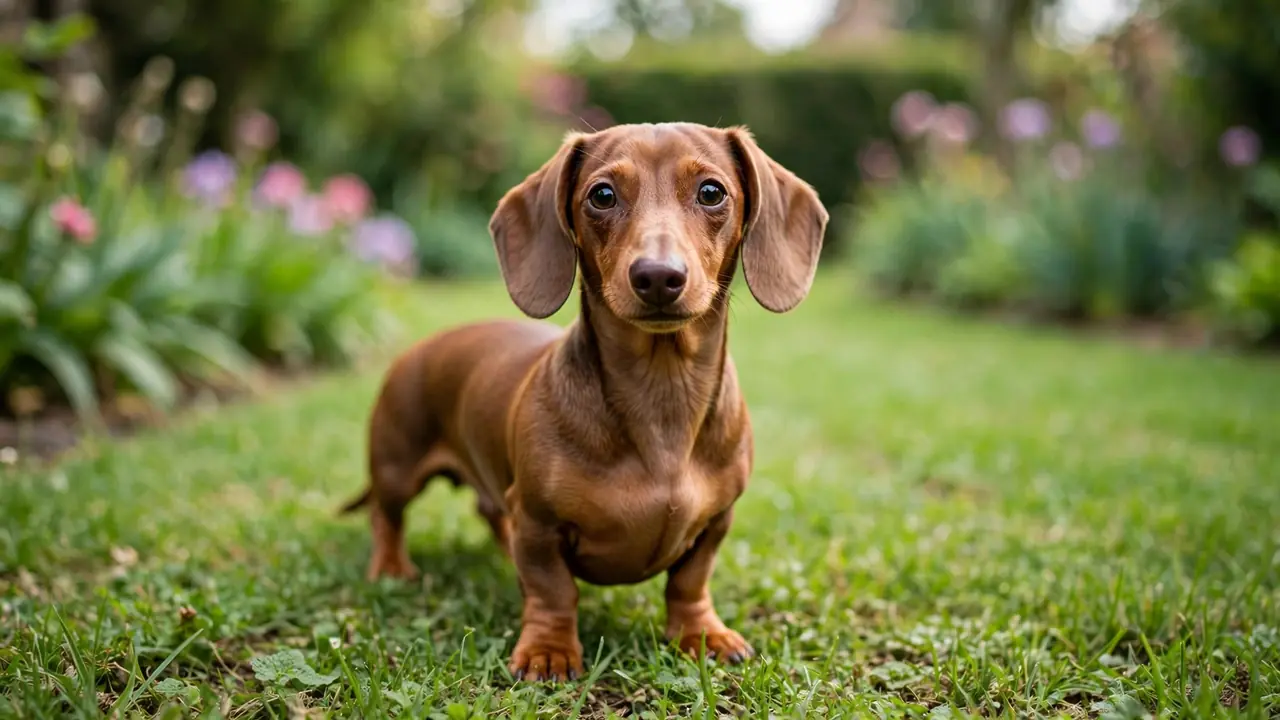
The Dachshund’s long back and short legs are the result of chondrodystrophy, a form of dwarfism that affects cartilage development. The same trait that gives the breed its shape also causes the discs between vertebrae to harden and degenerate far earlier than in other dogs. A disc that calcifies can rupture with little warning, pressing on the spinal cord.
When that happens, symptoms range from pain and reluctance to jump all the way to dragging the back legs or full paralysis. Cornell’s veterinary college notes that Dachshunds are among the breeds most predisposed to this type of disc disease, and episodes often strike young adult dogs, not just seniors. This is not a rare fluke. It is the breed’s signature health risk.
Prevention helps but cannot eliminate the risk. Keeping your Dachshund lean, using ramps instead of stairs, and lifting with support for both chest and rear all reduce strain. Responsible owners do all of this and still see IVDD strike. That gap between prevention and reality is exactly what insurance is for.
How Insurers Treat Back Issues
Pet insurance generally covers IVDD treatment, including diagnostics, medication, and surgery, as long as the condition was not pre-existing. That last phrase carries enormous weight for Dachshunds. Our guide to pre-existing condition rules explains the details, but the short version is that any back pain noted in the vet record before enrollment can taint future claims.
Some insurers go further with bilateral or related-condition exclusions. If your Dachshund had a neck disc issue before enrollment, a later lumbar disc episode might be linked to it and denied. This is why the cleanest possible medical record at enrollment matters so much for this breed. Every vague note about stiffness is a potential future denial.
Waiting Periods for Orthopedic and Spinal Conditions
Many policies impose a standard accident waiting period of a few days and an illness waiting period of around two weeks. For orthopedic and spinal conditions, some insurers add an extended wait of six to twelve months. IVDD sometimes falls into that extended category, so ask directly before you buy.
Our explainer on pet insurance waiting periods shows which companies keep the standard timeline and which extend it. If you are choosing between two similar plans, the shorter spinal waiting period is worth real money for a Dachshund owner.
What IVDD Treatment Costs
Mild episodes are managed conservatively with strict crate rest and medication, which still adds up across rechecks and drugs. Severe cases need advanced imaging and surgery. An MRI alone commonly runs into the low thousands, and published cost guides often cite roughly $3,000 to $7,000 for spinal surgery depending on region and complexity. Rehab after surgery adds more.
These numbers explain why your annual limit deserves serious attention with this breed. A single IVDD episode can consume most of a $5,000 limit before rehab even starts. Dachshunds also face repeat episodes, since one bad disc often means others are degenerating too. A higher limit, or an unlimited plan, matches the breed’s risk profile far better.
Diagnostic coverage matters as well. IVDD cannot be properly diagnosed without an MRI or CT scan in most cases. Confirm that MRI scans are covered under any plan you consider, and check whether the insurer requires pre-authorization that could delay emergency care.
What to Look for in a Dachshund Policy
Start with hereditary condition coverage. IVDD in Dachshunds is widely treated as hereditary, so confirm the policy covers hereditary conditions without sub-limits or carve-outs. A plan that technically covers IVDD but caps spinal surgery at a low amount is not really covering it.
Next, check how the insurer defines pre-existing conditions. The strictest companies exclude anything with related symptoms in the prior twelve months or even for life, while more forgiving ones only look back a year. For a breed where one in four dogs is affected, that distinction decides real claims. Our article on denied claims shows how often back issues end up in disputes.
Then look at the reimbursement structure. An 80 or 90 percent reimbursement rate on a $6,000 surgery bill is the difference between a manageable expense and a financial crisis. Pair it with a deductible you could pay tomorrow without stress. The cheapest premium is rarely the cheapest plan once a real claim arrives.
Typical Monthly Cost for Dachshunds
Dachshunds are small dogs, which helps, but their IVDD risk pushes premiums above the small-breed average. Many owners report paying roughly $25 to $55 a month for a young, healthy Dachshund on a standard accident and illness plan. As with every breed, age and zip code move that range, so get personal quotes.
Resist the temptation to buy the cheapest accident-only plan to save money. Accident-only policies generally do not cover IVDD, since it is classified as an illness, not an injury. For this breed, an accident-only plan skips the exact coverage you are buying insurance for. The cleanest medical record before the first back symptom plus real illness coverage is the combination that pays off.
When to Enroll Your Dachshund
Enroll in puppyhood, ideally around eight weeks. At that age the spine is healthy, the record is clean, and nothing can be labeled pre-existing. Given that IVDD often strikes young adults between ages three and six, a policy started in puppyhood will be seasoned and past all waiting periods when the risk peaks.
If you are adopting an adult Dachshund, enroll immediately and request the full prior vet history. Any mention of back pain, reluctance to jump, or abnormal gait before your start date can become a pre-existing exclusion. Knowing what is in the record lets you choose an insurer whose lookback rules treat you most fairly.
Frequently Asked Questions
Does pet insurance cover IVDD surgery for Dachshunds?
Yes, most accident and illness policies cover IVDD diagnosis and surgery as long as the condition was not pre-existing. Check for extended orthopedic waiting periods and confirm that hereditary conditions are covered without sub-limits. Those two clauses decide most IVDD claims.
Is IVDD considered a pre-existing condition?
Only if symptoms, diagnosis, or treatment appeared before your policy’s start date or during its waiting periods. A Dachshund with a clean record at enrollment is covered for future episodes. But a vet note about back stiffness from before enrollment can trigger a denial, so enroll while the record is clean.
How much does IVDD surgery cost without insurance?
Published veterinary cost guides commonly cite roughly $3,000 to $7,000 for spinal surgery, plus the MRI needed to diagnose it and rehab afterward. Total episode costs can climb higher with complications. This is why a high annual limit matters so much for Dachshund owners.
What is the best pet insurance for Dachshunds?
The best plan is one that covers hereditary conditions fully, has a short waiting period for spinal issues, offers a high annual limit, and defines pre-existing conditions narrowly. Compare those features rather than brand names, and read the policy wording on back and spinal conditions before you commit.
Can I get insurance after my Dachshund’s first IVDD episode?
You can, but the IVDD will almost certainly be excluded as pre-existing, along with related spinal issues depending on the insurer’s wording. Coverage for unrelated accidents and illnesses still has value. Enrolling before the first episode is far better, which is why puppyhood enrollment matters so much for this breed.
A Dachshund policy is not about generic coverage. It is about one specific, likely, expensive condition and whether your plan handles it cleanly. Choose hereditary coverage without games, a high limit, and early enrollment, and you will have done right by those long backs.