
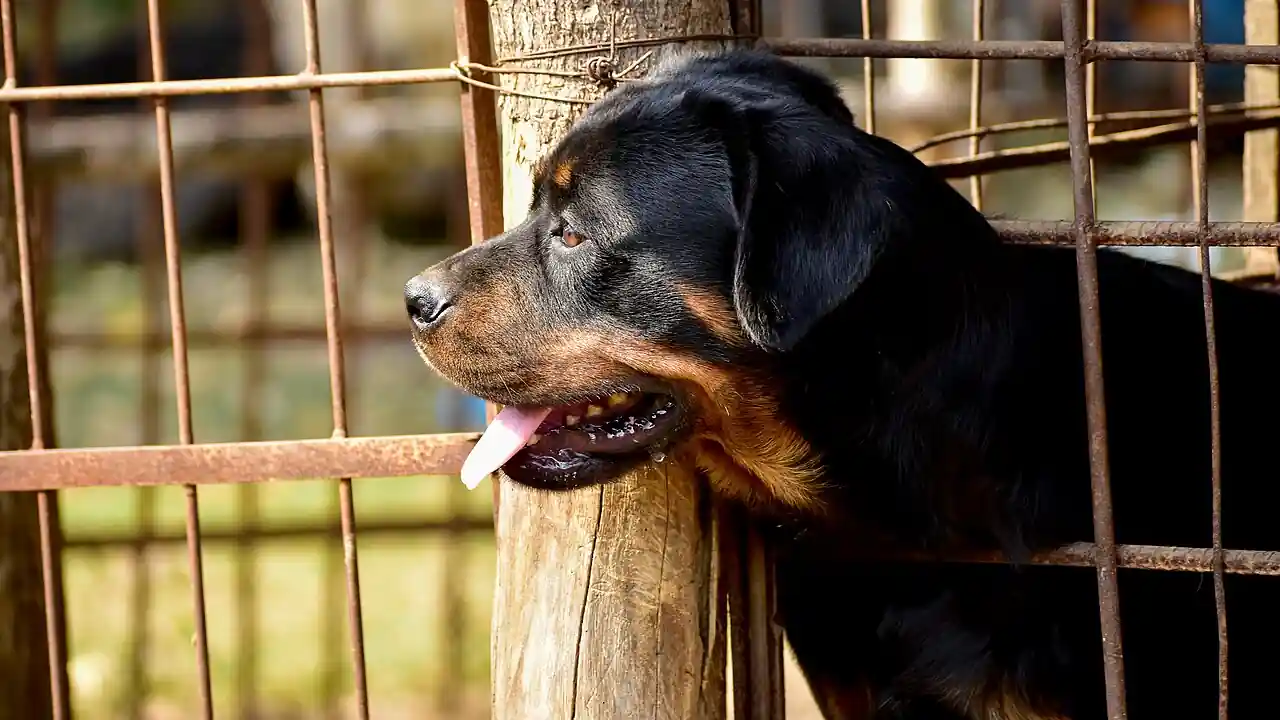
Rottweilers are powerful, loyal, and devoted family dogs. They are also one of the more expensive breeds to insure, and the reasons are written into their genetics. Cancer, cruciate injuries, and heart conditions show up in Rottweilers at rates that make insurers price accordingly.
This guide explains what drives Rottweiler insurance costs, why cancer coverage deserves special attention for this breed, and how to structure a policy that actually protects you. If Rottie premiums shocked you at first glance, this will show you where the money goes and how to spend it wisely.
Why Rottweilers Cost More to Insure
Insurers set prices from claims data, and Rottweiler claims data tells a clear story. The breed faces an elevated risk of osteosarcoma, an aggressive bone cancer that strikes large breeds hardest. Cruciate ligament tears are common in these powerful, heavy dogs. Heart conditions like subaortic stenosis add cardiac risk to the mix.
Each of those conditions carries a large average claim. Osteosarcoma treatment involving amputation and chemotherapy commonly runs well into five figures. A single cruciate surgery costs several thousand. When a breed reliably generates large claims, premiums reflect it. There is no way around the math, only ways to manage it.
Size compounds everything. At 80 to 130 pounds, Rottweilers need larger drug doses, bigger surgical teams, and more anesthesia than smaller dogs. Every procedure simply costs more at this weight. Many owners report paying roughly $50 to $90 a month for a young, healthy Rottweiler on a standard plan, with premiums climbing steeply as the dog ages.
Cancer Coverage: The Breed’s Biggest Question
Osteosarcoma Risk
Osteosarcoma is the most common bone cancer in dogs, and Rottweilers are among the breeds most predisposed. Cornell’s veterinary college lists Rottweilers alongside Great Danes and Saint Bernards as high-risk breeds. It typically appears as sudden lameness with swelling on a leg, often in middle-aged to older dogs, and it spreads aggressively.
Treatment usually means amputating the affected limb followed by chemotherapy, aimed at extending quality life rather than curing. Dogs adapt to three legs remarkably well, but the financial cost is severe. Published cost guides commonly cite five-figure totals for the full course of treatment. This single condition is the strongest argument for generous cancer coverage in a Rottweiler policy.
What Good Cancer Coverage Looks Like
Every accident and illness policy covers cancer treatment in principle, but the details decide real claims. Check that there are no per-condition sub-limits that would cap a $15,000 osteosarcoma course at a fraction of the cost. Confirm that chemotherapy, radiation, and advanced imaging are all included rather than excluded as specialist extras.
This is where the annual limit becomes the whole game. A $5,000 limit barely dents a serious cancer case. For Rottweilers, a $10,000 limit is a reasonable floor and unlimited coverage is worth serious consideration. The high annual limit is not optional for Rottweilers, it is the feature the entire policy is built around.
Also verify how the insurer handles chronic and ongoing conditions. Cancer treatment spans months, and you want continuous coverage across the policy year without mid-course surprises. Read the renewal terms too, since some insurers re-underwrite chronic conditions at renewal.
Cruciate Injuries and Joint Problems
Rottweilers tear cruciate ligaments at high rates. Their weight, power, and activity level stress the knee joint, and a sudden twist during play can rupture the ligament completely. TPLO surgery stabilizes the knee but costs several thousand dollars and demands weeks of strict rest, which is a project with a young Rottie.
Hip and elbow dysplasia also appear in the breed, though reputable breeders screen for both. As with other large breeds, insurers sometimes impose extended waiting periods for orthopedic conditions. Ask directly about cruciate and dysplasia waiting periods, because a six to twelve month wait changes the value of a policy started in adulthood.
Labrador owners face the same cruciate math, which shows how universal this risk is among big, athletic breeds. The lesson is identical: enroll before any limping, read the orthopedic waiting period, and keep the dog lean. Extra weight is the enemy of every large-breed knee.
Heart Conditions Worth Knowing
Subaortic stenosis, a narrowing below the aortic valve, is the cardiac condition most associated with Rottweilers. Severe cases cause fainting, exercise intolerance, and sudden death, sometimes in young dogs. Diagnosis needs an echocardiogram by a cardiologist, and management may involve lifelong medication.
Most policies cover cardiac diagnosis and treatment as long as the condition was not pre-existing. The catch is timing: heart murmurs are often detected at routine puppy visits, and a murmur noted before enrollment can complicate future cardiac claims. This is one more reason puppyhood enrollment matters so much for this breed.
Structuring the Right Rottweiler Policy
Start with the annual limit, as discussed, and work backward. A high limit with 80 percent reimbursement and a moderate deductible usually beats a low limit with 90 percent reimbursement for this breed. Run both configurations through the quote tool and compare the annual cost, not just the monthly premium.
Next, scrutinize the pre-existing condition definition. Rottweilers develop problems young often enough that a strict lifetime exclusion hurts more here than in healthier breeds. Our guide to pre-existing condition rules compares how insurers define and look back at prior symptoms.
Then check how reimbursement percentages work in practice, since 80 percent of a $12,000 cancer bill still leaves you with $2,400 plus the deductible. Make sure that remainder is an amount you could actually pay. Insurance that leaves an unpayable balance is not doing its job.
Finally, compare typical Rottweiler premiums across several insurers rather than accepting the first quote. Prices for high-risk breeds vary more between companies than prices for low-risk breeds, because each insurer’s claims data weights the breed differently. Three quotes minimum for a Rottie.
When to Enroll Your Rottweiler
Puppyhood, without question. Rottweiler premiums are already high, and they only rise with age. Enrolling at eight weeks locks in the lowest available rate and guarantees a clean medical record before any murmur, limp, or lump is ever documented. Given the breed’s cancer risk peaks in middle age, a policy started young will be fully seasoned when it matters most.
Adopting an adult Rottweiler? Enroll immediately after adoption and get the complete prior history. Lumps, limps, and murmurs are common enough in adult Rotties that you need to know exactly what is documented. If the history is murky, favor insurers with shorter lookback periods, and consider plans with minimal waiting periods to close the exposure gap fast.
Frequently Asked Questions
How much does Rottweiler insurance cost per month?
Many owners report paying roughly $50 to $90 a month for a young, healthy Rottweiler on a standard accident and illness plan. Premiums rise significantly with age and vary by location. Because Rotties are a high-risk breed, quotes differ more between insurers than for average breeds, so compare at least three.
Does pet insurance cover cancer treatment for Rottweilers?
Yes, standard accident and illness policies cover cancer diagnosis and treatment, including surgery, chemotherapy, and radiation, as long as the cancer was not pre-existing. The critical detail is the annual limit: choose a high or unlimited limit so a five-figure osteosarcoma course does not exhaust your coverage mid-treatment.
Why is Rottweiler insurance so expensive?
Claims data. Rottweilers have elevated rates of osteosarcoma, cruciate ligament tears, and heart conditions, all of which generate large claims. Their size also makes every procedure cost more. Insurers price all of that into the premium.
What annual limit do I need for a Rottweiler?
A $10,000 annual limit is a sensible minimum given the breed’s cancer and orthopedic risks. Unlimited annual coverage is worth the extra premium if your budget allows. Low limits like $5,000 can be exhausted by a single serious episode, leaving you exposed for the rest of the policy year.
Is pet insurance worth it for a Rottweiler?
For most owners, yes. The breed’s signature risks are exactly the high-cost, low-predictability events insurance handles best. One osteosarcoma course or cruciate surgery can exceed many years of premiums. The math only turns against insurance for owners with very large cash reserves and high risk tolerance.
Rottweiler insurance is not cheap, but it is rational. The breed’s risks are known, the expensive scenarios are specific, and a well-structured policy with a high limit turns a potential five-figure crisis into a manageable bill. Enroll young, compare quotes, and read the cancer fine print before you sign.